


Graham’s enduring idea was not simply to buy a falling stock. It was to demand a price that allowed for error in the estimate of business value.
Written by Ibraham
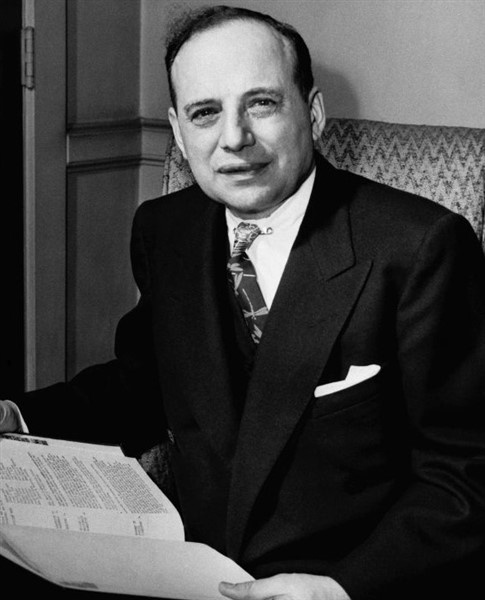
Benjamin Graham. Photo: Anonymous Unknown author. Wikimedia Commons source · Public domain. Used without AI alteration.
Benjamin Graham helped turn security selection from storytelling into a discipline built around evidence. Columbia Business School summarizes his framework with two connected ideas: a security has an intrinsic value justified by assets, earnings, dividends and prospects; the gap between that value and the market price creates a margin of safety.
The words sound simple. Applying them requires judgment. Intrinsic value is not printed on a stock certificate, and a low price does not automatically create value. Graham’s contribution was to make uncertainty part of the purchase decision rather than hide it behind a precise forecast.
Price and value are different questions
Market price answers what buyers and sellers agree on now. Intrinsic value asks what the underlying business can reasonably support. An analyst may examine cash, debt, assets, normalized earnings and the durability of the company’s economics. Every input can be wrong, which is why the margin of safety matters.
Suppose an investor estimates a business at $100 per share. Paying $99 leaves almost no room for an error in earnings, interest rates or competitive conditions. Paying $65 creates a 35% gap between price and the estimate. That gap is not a guaranteed profit. It is a buffer against imperfect analysis.
Why “cheap” can still be dangerous
A stock can trade at a low multiple because its earnings are temporary, its balance sheet is weak or its industry is shrinking. Book value can overstate what factories, inventory or goodwill would produce in a sale. Debt can give creditors most of the economic value even while common shares look statistically inexpensive.
Graham’s method therefore begins with financial statements, not a price chart. The investor must ask what would have to be true for the estimate to hold and what could permanently impair the capital. A margin of safety cannot rescue an estimate built on unreliable accounts or unrealistic growth.
From Security Analysis to investor education
Graham and David Dodd published Security Analysis in 1934, during a period shaped by the market crash and the Great Depression. In 1949, The Intelligent Investor brought the distinction between investing and speculation to a wider audience. Columbia’s archives preserve the intellectual lineage that became known as value investing.
The historical importance is not that every later investor copied one formula. The method changed as businesses became more dependent on brands, networks and intangible assets. The continuing principle is to compare a defensible estimate of value with the price paid and to admit that the estimate has limits.
The portfolio is part of the margin of safety
Even careful analysis will produce mistakes. Diversification prevents one incorrect estimate from deciding the outcome of an entire portfolio. Position size matters as much as the purchase price. A heavily concentrated “cheap” position may carry more risk than a smaller holding bought at a less dramatic discount.
Time horizon matters too. A business can remain undervalued, and a market decline can take a sound company lower. Investors who need the money soon may be forced to sell before the thesis is resolved. That is why valuation should be connected to liquidity, debt and the investor’s actual goal.
A practical Graham checklist
Write down the earnings and balance-sheet assumptions behind the valuation. Stress them rather than using only the optimistic case. Separate a cyclical decline from permanent deterioration. Check whether management is issuing shares, adding debt or allocating capital in ways that change the value per share. Finally, decide in advance what evidence would prove the thesis wrong.
For a modern comparison of disciplined investing structures, see our target-date fund versus three-fund portfolio guide. Graham’s broader historical setting also connects with the WealthPast people and fortunes archive.
The margin of safety is useful because it treats humility as a financial tool. It asks the investor to pay a price that can survive some disappointment. It cannot turn uncertainty into certainty, but it can make the consequences of being wrong more manageable.
Sources
- Columbia Business School — Value Investing History
- Columbia University — Benjamin Graham
- Columbia University Libraries — Benjamin Graham papers
Explore the complete Benjamin Graham profile in the WealthPast archive.