


Franco Modigliani’s life-cycle theory explains saving as a way to move resources across different stages of life. Income and spending needs rarely arrive in the same pattern: workers may earn more during mid-career and draw down assets in retirement. The model organizes that problem, but it does not say every household has equal capacity to save or that retirement outcomes are certain.
Written by Ibraham
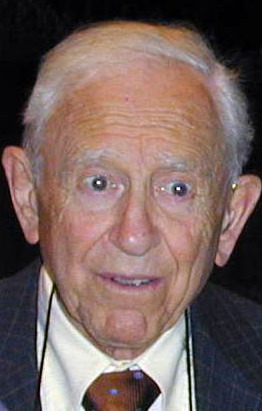
From displacement to MIT
Modigliani was born in Rome on June 18, 1918. After fascism and Italy’s racial laws disrupted his life, he and Serena Calabi reached the United States in August 1939. He joined MIT in 1962, became an Institute Professor in 1970 and professor emeritus in 1988. He died in Cambridge, Massachusetts, on September 25, 2003. The 1985 economics prize recognized his analyses of saving and financial markets.
These achievements describe research, not an audited personal fortune. Prize money mentioned in MIT’s obituary is not a complete net-worth record. The Franco Modigliani profile preserves the biographical timeline and makes that distinction explicit.
The model compares lifetime resources with lifetime needs
A simple life-cycle plan begins with expected resources, not this month’s paycheck alone. Imagine a fictional worker expecting $60,000 of after-tax income for 30 working years and $20,000 for 20 retirement years. Ignoring investment returns, inflation and uncertainty, lifetime income totals $2.2 million: $1.8 million while working plus $400,000 in retirement. Spread across 50 years, that is $44,000 a year before other obligations.
The arithmetic is deliberately incomplete. Housing, children, health, taxes, job loss, longevity and bequests change the plan. Borrowing constraints can prevent a young household from smoothing consumption, while a low-income household may have no discretionary surplus. The theory is a framework for examining timing, not a moral judgment about people who cannot save.
Retirement withdrawals add market-order risk
Even a carefully accumulated portfolio can produce different results depending on when losses occur. Our sequence-of-returns risk example explains why early withdrawals during a decline can damage a retirement plan more than the same average return received in another order.
Product choice must therefore follow the liability. A target-date fund versus three-fund portfolio comparison can organize diversification and rebalancing, but neither structure guarantees that lifetime resources will cover lifetime consumption.
Modigliani–Miller is a theorem with conditions
Modigliani’s work with Merton Miller addressed corporate financing. Under restrictive assumptions, the mix of debt and equity does not by itself determine firm value. That result is useful because it forces analysts to identify why financing might matter in reality: taxes, bankruptcy costs, information, agency conflicts and financing constraints.
Suppose a fictional company worth $100 million has no debt. Replacing $30 million of equity with $30 million of debt does not mechanically create another $30 million of enterprise value. Under the theorem’s idealized conditions, the claims are rearranged. In the real world, interest deductions, distress risk and lender restrictions can change cash flows and risk, so the conclusion cannot be copied without checking the assumptions.
Saving models do not promise a single national rate
Age structure, pensions, income expectations, family transfers, public policy and credit access can all affect aggregate saving. The Milton Friedman permanent-income lesson offers a related but distinct way to connect expectations and consumption. Neither theory turns a forecast of lifetime income into certain cash.
The durable lesson from Modigliani is to match the time pattern of resources with the time pattern of needs, then state the frictions that the clean model omits. For households, that means uncertainty and unequal capacity to save. For firms, it means explaining exactly which real-world departure makes financing relevant.
Sources and Method
- MIT News — Franco Modigliani: 1918–2003
- NobelPrize.org — Franco Modigliani facts
- NobelPrize.org — Life Cycle, Individual Thrift, and the Wealth of Nations
Checked November 9, 2026. The income and financing examples are original illustrations with simplifying assumptions, not personal financial advice or company valuations.