


The first Vanguard index fund for individual investors missed its fundraising target badly. Its financial logic proved far more durable than its launch suggested.
Written by Ibraham
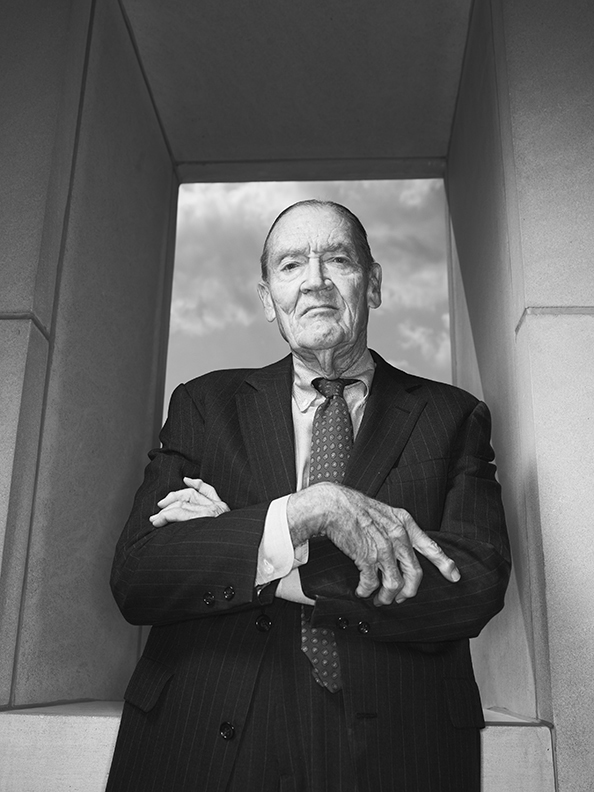
John C. Bogle. Photo: BillCramer. Wikimedia Commons source · CC BY-SA 4.0. Used without AI alteration.
On August 31, 1976, John C. Bogle launched First Index Investment Trust, the fund now known as Vanguard 500 Index Fund. Vanguard says the offering raised just $11.3 million against a $150 million target. The small opening did not look like the beginning of a financial revolution. It looked like a product that the market had declined to embrace.
The lesson is larger than one fund. Bogle’s contribution was to make a previously institutional idea available to ordinary investors in a simple vehicle: hold a broad group of companies, keep operating and trading costs low, and accept the market’s result instead of repeatedly paying someone to try to beat it.
The economics behind the index fund
An investor receives the return earned by the underlying portfolio after expenses, trading costs and taxes. Costs therefore create a basic arithmetic constraint. If two portfolios own similar securities and earn the same gross return, the less expensive one leaves more for its shareholders. The advantage is small in one year, but it compounds over decades.
Indexing also changes where the investor takes risk. It reduces reliance on selecting one winning manager or a handful of stocks. It does not remove market risk. A broad stock index can decline sharply, remain expensive for years or become concentrated in its largest companies. Diversification spreads company-specific risk; it cannot promise a positive return on a particular date.
Why the $11.3 million launch mattered
The gap between the $150 million target and the $11.3 million raised shows how unfamiliar the proposition was. Active management dominated the retail fund market, and “average” sounded unattractive. The index fund’s argument was subtler: before fees, active investors collectively make up the market; after fees, the higher-cost group must receive less in aggregate.
Vanguard’s own history describes Bogle as the person who democratized indexing for individual investors. Institutional index strategies existed before 1976, so accuracy matters: he did not invent every form of indexed investing. He built a retail product and an organization designed to deliver it at scale.
The Vanguard ownership structure
Bogle’s second financial idea was organizational. Vanguard’s U.S. funds own the management company, and fund shareholders own the funds. That structure does not eliminate every conflict, but it removes outside public shareholders who would otherwise expect profits from the management company. The intended result is that scale can be returned to investors through lower costs.
This distinction also prevents a common historical error. Assets managed by Vanguard belonged to fund investors. They were never Bogle’s personal fortune. The growth of a fund company may demonstrate the reach of his model, but assets under management and personal net worth are different measurements.
What investors can use today
Bogle’s framework begins with controllable inputs. Investors cannot set next year’s market return. They can compare expense ratios, diversify, limit unnecessary trading and choose an allocation they can hold through a downturn. Those choices do not guarantee success, but they reduce avoidable friction.
An index label alone is not enough. Investors should still ask what the index owns, how concentrated it is, whether the fund tracks it efficiently and how the product fits the goal. Our guide to index mutual funds versus index ETFs explains the product choices, while the expense ratio and tracking-difference guide shows why the headline fee is only one part of implementation.
The 1976 launch is a useful business case because adoption and sound economics do not always arrive together. A product can begin with weak demand and still succeed if its structure solves a persistent problem. Bogle’s answer was not a prediction about which stock would win. It was a system for keeping more of whatever return the market delivered.
Sources
- Vanguard — Our history
- Vanguard — 50 years, 50 facts: indexing since 1976
- Vanguard — 50th anniversary of Vanguard 500 Index Fund
Explore the complete John C. Bogle profile in the WealthPast archive.